Can I Get a Rolex Loan Even If I Haven’t Worn It in a Year?
Yes. A Rolex does not usually need to be in regular rotation to qualify as collateral. A lender will care more about what the watch is, whether it is authentic, its condition, and what it could reasonably sell for than whether you wore it last month.
That can make a watch loan useful when a time-sensitive purchase comes up: you need cash now, but you would rather not give up a watch you may want back. The tradeoff is straightforward. You get money for a limited period, and you risk losing the watch if you do not repay the loan under the agreed terms.
In Miami, that calculation can feel especially urgent during Art Week, when a piece or purchase may be available only briefly. The sensible move is to check the numbers before you commit—not borrow based on the price you hope the watch will bring.
Does an unworn Rolex qualify for a loan?
Often, yes. A watch being unworn for a year does not automatically make it ineligible. If anything, it may have less wear than a watch used every day, though storage conditions still matter. Moisture, scratches, a damaged crystal, missing links, or service needs can affect a lender’s assessment.
Expect an on-site inspection. The lender may examine the watch’s reference and serial details, movement, case, bracelet, clasp, dial, and overall condition. Box, papers, receipts, service records, and extra links may help establish its history and completeness. Their absence does not necessarily end the conversation, but it can affect the offer or the verification process.
Be ready to show that you own the watch and can legally pledge it. Bring identification and any purchase or service documentation you have. Requirements vary by lender, so ask what to bring before making the trip.
Why a Rolex can work as collateral
A Rolex is a recognizable luxury asset with an active resale market. That does not mean every model is equally easy to sell, or that every watch will hold its retail price. It does mean a lender may have more public pricing information and potential resale channels to consult than they would for a niche item with few comparable sales.
For a borrower, the appeal is control. You can use a watch as collateral for short-term cash without selling it outright. If you repay according to the contract, you can recover the watch. If you sell, the transaction is permanent: you receive the proceeds and give up ownership.
Neither option is automatically smarter. A loan can cost more than expected if the term, interest, or fees are unfavorable. A sale may be the cleaner choice if you have no strong reason to keep the watch or no realistic repayment plan.
Start with secondary-market value—not the retail price
The number that matters is the watch’s likely secondary market value: what comparable examples are actually being offered or sold for, adjusted for model, reference, year, condition, completeness, and seller channel. The original retail price is not a reliable shortcut. Nor is a high asking price for a single listing proof that a buyer will pay that amount.
Use publicly tracked pricing as a starting point. Price-tracking services and public marketplace listings can help you see recent trends and compare similar references. Check the exact reference and condition where possible. A steel sports model with a complete set is not a clean comparison for a different metal, dial, production year, or watch with missing parts.
Public data has limits. Asking prices can sit unsold, and private sales may not appear in trackers. A lender’s offer will also account for the cost and time of verifying, holding, and potentially reselling the watch. So expect a collateral offer to be below an optimistic retail listing—not a promise to match it.
A Daytona in a safe example
Say you have a Daytona that has been sitting in a safe for a year. It is unworn, has its box and papers, and appears to be in good condition. Before asking for a loan, you check publicly tracked pricing for the same reference and compare it with current listings and, where available, completed sales.
For illustration only, imagine your research suggests comparable examples trade around $25,000. That is not a quote, a current market claim, or a guarantee of what your watch is worth. An on-site inspection could produce a different valuation if the watch has a service issue, the paperwork does not match, or the comparisons are not truly like-for-like. The lender may then offer a loan amount below its own assessed resale value.
The useful question is not, “What is the biggest number someone might offer?” It is, “How much do I need, what will this cost to repay, and can I meet the deadline without putting the watch at risk?”
What happens during on-site authentication and valuation?
Reputable providers should explain their process and let you understand what they are checking. Authentication and valuation on-site may include examining identifying details, https://technivorz.com/should-i-bring-service-records-to-sell-my-rolex/ condition, originality, and whether the watch’s components appear consistent with its reference. The evaluator may also review paperwork and compare the watch with current market data.
Do not assume an online estimate is a final offer. Photos cannot reliably show every detail, and an in-person inspection may change the valuation. Ask whether the on-site assessment is free, whether you can decline the offer without a fee, and whether the watch stays with you until you accept the written terms.
For an expensive watch, arrange the appointment directly with a professional business. Skip parking lot meetups and informal handoffs. Ask where the inspection takes place, how the watch is secured if accepted, and what documentation you receive.

Loan or sale: which fits your situation?
Option What you get Main tradeoff May fit if… Use the watch as collateral Short-term cash while retaining a path to reclaim the watch Interest, fees, and a repayment deadline; default can mean losing the watch You want the watch back and can repay on time Sell the watch Sale proceeds without a loan repayment obligation You permanently give up ownership and may not receive your target price You no longer want the watch or need a simpler, final transactionSelling an unworn Rolex can make sense if it is not your style, does not fit your collection, or has been forgotten in a safe. The proceeds might help fund a watch you will actually wear—or another priority. That is not the same as selling under pressure. Get more than one informed offer where practical, understand any selling fees, and compare the net amount you would receive.
A loan is more appropriate when the watch has personal value and you have a defined way to repay. “I’ll figure it out later” is not a repayment plan. If the expected cash flow is uncertain, selling may be less costly and less stressful.
Art Week timing: buying power has a clock
During Art Week, a desired work, collectible, or watch may be held only until Sunday—or for a few hours. A loan can create buying power without forcing an immediate sale of an asset you want to keep. But urgency can make expensive terms look acceptable when they are not.
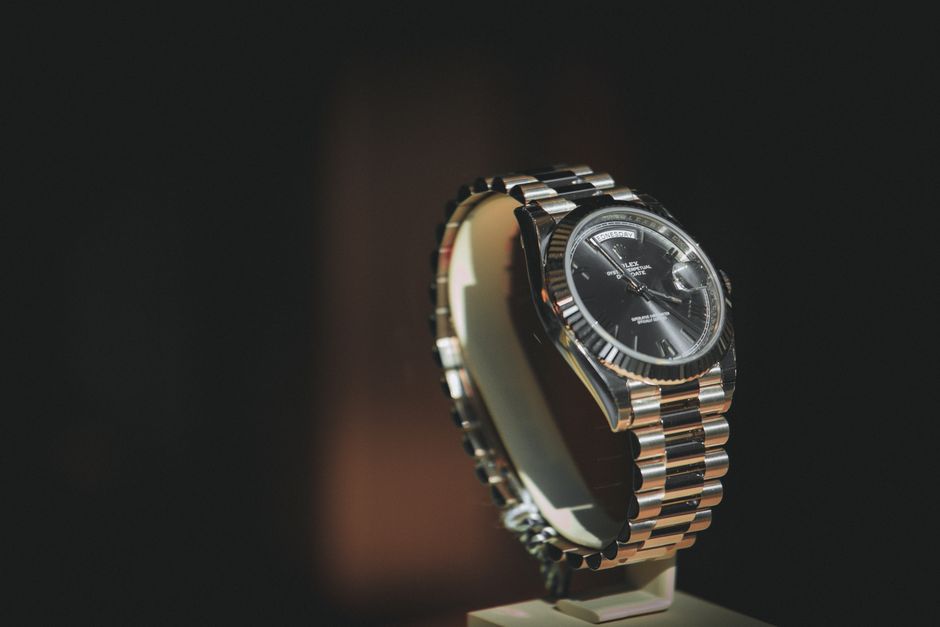
Before putting your Rolex on the counter, write down the purchase deadline, the amount you need, and the date you can repay. Then compare that plan with the loan’s full cost and term. If repayment depends on a future sale, bonus, or deal that is not certain, pause. Do not borrow more than you can repay just because the lender is willing to advance it.
Ask whether the lender can complete authentication, valuation, and paperwork within your time window. Do not count on same-day funding unless the provider confirms it for your particular case. And do not hand over the long term watch loan watch until you understand what happens if you miss a payment or the final due date.
Questions to ask before you sign
- What is the exact loan amount, interest rate, and total amount due?
- Are there storage, appraisal, service, or other fees? When are they charged?
- What is the due date, and can the term be extended? What would an extension cost?
- What happens if I pay late or cannot repay by the deadline?
- How is the watch stored, insured, and documented while it is held?
- Can I decline the offer after the inspection without paying a fee?
- What proof of ownership or identification do you require?
Read the contract, not just a summary on a screen. Confirm that the watch’s identifying information and the agreed terms are recorded correctly. If something is unclear, ask for an explanation in plain language before signing.
A practical checklist for a Rolex loan
- Identify the watch. Note the reference, approximate purchase date, condition, and what accessories or records you have.
- Check comparable pricing. Use public secondary-market data for the exact reference, and distinguish asking prices from completed sales when possible.
- Get an in-person assessment. Ask what authentication and valuation cover and whether an estimate is binding.
- Compare the loan with a sale. Calculate the amount you would receive and the total repayment cost, not just the headline advance.
- Set a repayment limit. Choose a payment plan that works with money you expect to have—not money you hope might appear.
- Protect the handoff. Use a professional location, review the contract, and get written documentation of the watch and its custody.
The bottom line
Yes, you may be able to get a Rolex loan even if you have not worn the watch in a year. An unworn watch can still be valuable collateral, but its age, condition, authenticity, completeness, and current secondary market value matter more than how recently it left the safe.
Use public pricing to prepare, then treat on-site authentication and valuation as the real checkpoint. A loan can preserve your option to reclaim a watch; a sale can turn an unused asset into cash without leaving a repayment obligation. If Art Week has a deadline—held until Sunday, for example—make sure the clock does not push you into terms you cannot comfortably meet.