How Do I Know If My Rolex Is in Good Condition for a Loan?
It’s Friday night before a major event at WestWorld of Scottsdale. You have a car purchase, an auction plan, or another short-term cash need—but you would rather not sell your Rolex. Could the watch help you free up cash?
In many cases, yes. A Rolex can be a liquid luxury asset and may qualify for a rolex collateral loan, depending on its identity, condition, market demand, and the lender’s requirements. “Good condition,” though, does not simply mean that the watch looks nice on your wrist. A lender needs to establish what it is, whether it is authentic, how complete it is, and what it could reasonably be worth in the current market.
Here is the tradeoff: a collateral loan may provide speed and privacy while letting you keep ownership, but the convenience comes with interest and repayment terms. Before you hand over a watch—or count on it to cover a time-sensitive expense—understand how condition is assessed and what the process involves.
What “Good Condition” Means for a Rolex Loan
For lending purposes, condition is a practical assessment of the watch’s identity, function, originality, and resale appeal. A watch does not have to be pristine to be considered. It does need to be evaluated accurately.
- It can be identified: The model, reference, metal, and other details can be checked against the watch itself and any available documentation.
- It appears authentic: The watch and its components can be examined as part of a watch authentication process.
- It runs as expected—or its issues are understood: A stopped or poorly functioning watch may still have value, but mechanical problems can affect the offer.
- Its condition can be described clearly: Scratches, dents, bracelet stretch, dial condition, and evidence of polishing all matter.
- Its value can be supported by current market evidence: The model’s demand and recent pricing help establish a realistic collateral value.
That last point matters. “Rolex” is not a price. A steel sports model, a precious-metal dress watch, and a vintage reference can behave very differently in the resale market. The condition and demand for the specific watch—not the brand name alone—shape the lender’s assessment.
Start With the Watch Itself
Check the reference and identifying details
If you have the original paperwork, service records, or purchase receipt, gather them. They can help document the watch’s history and make the review more straightforward. Papers are useful, but they do not replace examination of the watch, and a watch without its box or papers is not automatically ineligible for a loan.
Do not try to open the case or remove components to find identifying information. Leave that work to a qualified professional. Opening a watch without the right tools and experience can damage it or introduce dust and moisture.
Look at the dial, hands, bezel, and bracelet
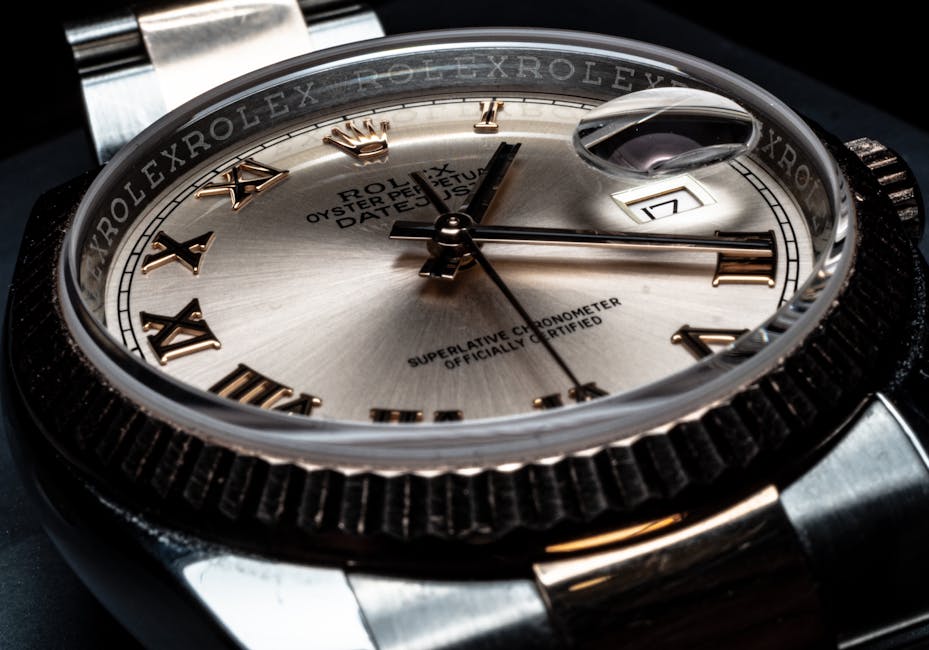
Under ordinary light, note the visible condition without attempting to repair anything. Look for cracks, chips, heavy scratches, missing markers, loose components, or damage around the bezel and crystal. Check whether the bracelet clasp closes securely and whether the bracelet feels unusually loose.
Everyday wear is normal. The important distinction is between ordinary marks and condition issues that could affect function, authenticity, or resale demand. A lender may also care whether parts appear original to the watch. Aftermarket or replacement components can influence valuation, even if they make the watch look newer.
Be honest about function
If the watch is running, say so—but do not assume that keeping time today proves it is mechanically sound. If it is running slow, stops, has a damaged crown, or has not been serviced in years, disclose that. A professional inspection can identify concerns that a casual check cannot.

Do not pay for a service or polish solely because you think it will increase the loan offer. Service costs may not be recovered in the appraisal, and polishing can remove metal or soften case edges. Ask the lender whether service is necessary before spending money on work.
How Watch Authentication and Valuation Usually Work
An appraisal for a loan is not the same as an insurance replacement estimate, a retail asking price, or a guaranteed auction result. The lender is assessing the watch as collateral and considering how confidently it can be authenticated and what it may be worth under its own lending criteria.
- Initial details: You share the model information you know, the watch’s condition, and whether you have a box, papers, or service records.
- Physical examination: A specialist inspects the watch and relevant components. This is where watch authentication and condition review become central.
- Market review: The specialist considers comparable sales, current demand, and global secondary market pricing tracked publicly, where applicable.
- Loan valuation: The lender determines the collateral value it is willing to use, then explains the amount it may offer and the loan terms.
- Agreement and custody: If you accept, review the contract, repayment schedule, fees, interest, and how the watch will be stored while the loan is outstanding.
Public pricing data can help provide context, but it is not a promise of what your watch will sell for or what a lender will advance. Asking prices may differ from completed sales, and different examples of the same reference may have different condition, accessories, service history, or desirability.
scottsdale.org What is reviewed Why it matters What you can prepare Identity and authenticity The lender needs confidence in what is being accepted as collateral. Original paperwork, receipts, service records, and accurate model information. Physical condition Damage, wear, or mechanical concerns can affect value and marketability. A clear description of known issues; do not conceal or attempt repairs. Originality and completeness Original components and accessories may affect collector interest and valuation. Box, papers, extra links, tags, and any replaced parts or service details. Current market demand Different references have different liquidity and resale prospects. The exact reference, configuration, and any details that distinguish your watch.Why Rolex Can Work as Collateral—and What Liquidity Really Means
Rolex is widely recognized, and many models trade in an established secondary market. That can make a well-identified, authentic watch easier to evaluate and potentially more liquid than a niche luxury item with a smaller buyer pool.
Liquidity does not mean every Rolex can be turned into cash for the same amount, on the same schedule, or without cost. A lender still has to authenticate the watch, assess its condition, and decide how much risk to take. The loan amount will generally be lower than an optimistic retail asking price because the lender must account for its own risk, costs, and loan terms.
Think of the watch as a way to access cash without selling it outright—not as a guaranteed source of a particular sum. If you repay according to the agreement, you can generally recover your watch under the contract’s terms. If you do not, the lender may have rights to keep or sell the collateral. Read the default and redemption provisions before signing.
Speed and Privacy Versus the Interest Rate Tradeoff
People often consider a collateral loan when timing matters. Perhaps you need cash before a car purchase, a business payment, or an auction-week opportunity. Compared with arranging some forms of traditional financing, a specialized lender may be able to move quickly once the watch has been reviewed. The actual timeline depends on the lender, the watch, authentication needs, and how quickly you can provide information.
A collateral loan can also offer a more private path than listing a watch publicly for sale. You are not advertising the watch to buyers or negotiating with multiple strangers. But privacy and convenience do not make the financing free. Interest, fees, loan duration, renewal options, and the consequences of late or missed payments all matter.
Compare the total cost over the period you expect to borrow, not just a headline rate. Ask for the repayment amount by a specific date and get the answer in writing. If the loan is meant to bridge a short gap, make sure your cash plan accounts for the repayment date—not only for receiving the funds.
Planning Around Barrett-Jackson and WestWorld of Scottsdale
In Scottsdale, timing can get compressed around major collector events. Barrett-Jackson and activity at WestWorld of Scottsdale can bring buyers, sellers, and enthusiasts into town at the same time. That is exactly when a watch owner may be tempted to make a quick decision.
Do not wait until the day before an auction or purchase to find out whether your Rolex qualifies. Start early enough to allow for authentication, valuation, document review, and any questions about condition. A lender’s process is not the same as walking into a booth and getting an instant final number.
- Contact the lender before the event rush and ask what information it needs.
- Confirm the current review timeline and whether an in-person appointment is required.
- Bring the watch and any box, papers, service records, or spare links you have.
- Ask when funds may be available if you accept the offer, rather than assuming same-day funding.
- Build a repayment plan before using the loan to bid or make a purchase.
This planning is especially useful if you are comparing a watch loan with another source of cash. A bank credit line and an asset-backed loan are not interchangeable: one is based on a credit arrangement, while the other is secured by a specific asset. Compare the terms, timing, and consequences of each option on their own merits.
Getting a Watch Appraisal in Scottsdale
If you are seeking a watch appraisal Scottsdale owners can use to make a lending decision, ask what the appraisal covers. Is the appointment for an insurance estimate, a resale opinion, or a collateral-loan valuation? Those are different purposes and may produce different figures.
Ask whether the evaluation includes watch authentication, a condition assessment, a review of relevant market data, and a written explanation of the loan terms. Diamond Banc is one company to consider contacting for information about a watch-backed loan process. Confirm its current requirements, timing, fees, and storage arrangements directly before moving forward.
A useful conversation should be specific. Ask what happens if the watch needs further review, whether a loan can be declined after examination, and how the lender handles the watch while it is in its care. You should leave knowing the proposed amount, the total repayment obligation, the due date, and what happens if you cannot pay on time.
A Practical Checklist Before You Apply
- Identify the model and reference as accurately as you can.
- Gather paperwork, service history, box, spare links, and other accessories you still have.
- Write down any known repairs, replacement parts, timing issues, or damage.
- Do not polish, open, or repair the watch without professional advice.
- Ask whether the evaluation is for collateral lending, not insurance replacement value.
- Request the loan amount, interest, fees, term, and repayment total in writing.
- Confirm the storage, insurance, redemption, and default terms before signing.
- Plan around a specific cash need and repayment date, especially during auction week.
The Bottom Line
Your Rolex may be in good enough condition for a loan even if it shows normal wear. What matters is whether a qualified specialist can authenticate it, understand its condition and originality, and support a current valuation for that particular reference.
Before a Friday-night auction decision or a time-sensitive purchase, give yourself room to compare the offer and the full cost. A Rolex collateral loan can free up cash while letting you retain ownership, but it is still borrowing against an asset you care about. Know the timeline, know the terms, and make the repayment plan before the watch leaves your hands.