How Is Interest Calculated on a Watch-Secured Loan?
A watch-secured loan lets a borrower use a watch as collateral for a loan. The lender assesses the watch, decides how much it is willing to lend against it, and charges interest according to the loan agreement. The watch’s value matters, but it does not by itself determine the interest charge: the principal, rate, billing method, fees, and repayment schedule all matter too.
For a small business owner, this kind of financing may help cover a cash-flow timing gap—for example, when payroll or a supplier invoice comes due before a customer pays. It can be quicker to arrange than some bank financing, but speed may come with a higher cost or a shorter repayment window. Before pledging a watch, understand exactly how the lender calculates monthly interest charges and what happens if you cannot repay on time.
The Basic Interest Calculation
Many short-term collateral loans charge simple interest on the outstanding principal. A common estimate is:
Interest = principal × annual interest rate × time
If a lender charges a 12% annual rate on a $25,000 loan for a full month, a simple monthly estimate is $25,000 × 0.12 ÷ 12, or $250. That is an illustration, not a market quote. Actual monthly interest charges depend on the rate and the contract’s method for counting days.
For a loan that calculates interest daily, a lender might use a 365-day year. At the same illustrative 12% rate, 30 days of interest on $25,000 would be about $246.58: $25,000 × 0.12 × 30 ÷ 365. A lender using a 360-day convention, or a different billing cycle, will produce a different amount. Ask which method the agreement uses.
What it means for payroll
Interest reduces the cash available for wages or operating bills, so budget the payment date and amount before using loan proceeds to cover payroll.
Monthly Interest Charges Are Not Always the Same as a Monthly Payment
A monthly interest charge is the cost of borrowing for that billing period. It is not necessarily the full amount you must pay that month. Some agreements require interest-only payments, with the original principal due later. Others require principal payments along with interest, or allow the borrower to repay the loan at maturity.
With an interest-only structure, a borrower might pay the monthly interest while the principal remains unchanged. Using the illustrative $25,000 loan above, a $250 interest payment would not reduce the $25,000 balance. The borrower would still need to repay the principal under the agreement. If interest is added to the balance instead of paid, the amount owed may grow, depending on the contract.
Check whether the lender charges interest:
- On the original loan amount or on the remaining principal balance.
- From the day funds are released, the day the contract is signed, or another stated date.
- For actual days outstanding, a standard month, or another billing convention.
- Only until repayment, or through a minimum term or required interest period.
Also ask whether the lender permits early repayment without a fee, and whether early payoff reduces the interest you owe. “No prepayment penalty” and “interest stops accruing when you repay” are not identical promises; get the payoff calculation in writing.
What Determines the Rate Based on LTV?
Loan-to-value ratio (LTV) compares the loan amount with the lender’s assessed value of the collateral:
LTV = loan amount ÷ assessed collateral value × 100
If a lender assesses a watch at $40,000 and offers a $20,000 loan, the LTV is 50%. The lender may use LTV as one factor when setting the rate and maximum loan amount. A lower LTV gives the lender a larger value cushion if it has to sell the watch, but it does not guarantee a particular rate. Lenders also consider the watch’s marketability, condition, documentation, storage requirements, loan term, and borrower or transaction details.
The assessed collateral value is not necessarily the watch’s retail price, the amount originally paid, or the highest online asking price. A lender may estimate what it could realize from a sale, accounting for resale costs, market movement, and time needed to find a buyer. Ask for the valuation basis and the loan-to-value calculation, rather than relying on a general claim about what the watch is “worth.”
What it means for payroll
A lower LTV can limit how much cash you can borrow, so compare the amount you can actually draw with the payroll gap you need to cover.
Why a Rolex’s Secondary-Market Liquidity Matters
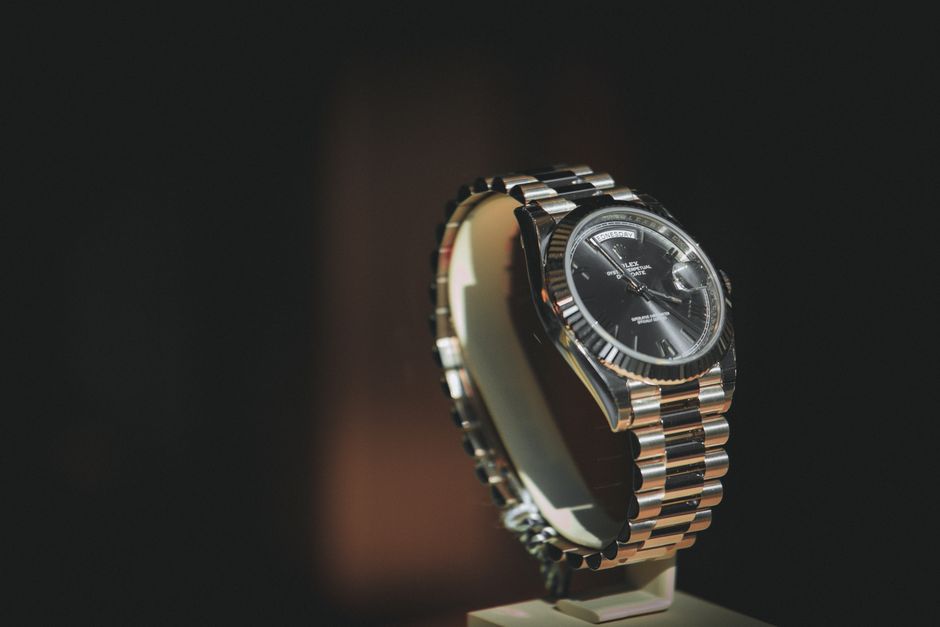
Rolex watches often have an active secondary market, but liquidity varies by model, reference, condition, completeness, and buyer demand. Here, liquidity means how readily a lender or seller can convert the watch into cash without taking an unusually large discount or waiting an uncertain length of time. A model with regular transaction activity may be easier to value and resell than a less familiar or less actively traded watch.
Publicly tracked secondary-market pricing data can help show price trends and provide context for comparable watches. It is a reference tool, not a guaranteed sale price. Public data may reflect asking prices, reported transactions, estimates, or different definitions of a comparable model. Prices can also shift with market demand, currency changes, and the condition or completeness of the specific watch.
For a useful comparison, match the reference number and relevant attributes as closely as possible. The presence of original papers, box, service records, and accessories may affect the lender’s assessment, but each lender applies its Have a peek at this website own standards. Do not assume that a published market index or online listing represents the amount a lender will advance.
Ask the lender how it uses pricing data: Does it review recent completed sales, dealer bids, auction results, or a combination? Does it discount the estimated resale value to account for selling costs and market risk? The answers help explain the assessed value behind the LTV and, in turn, the proposed loan amount and rate.
Authentication and Condition Checks
A qualified specialist should authenticate the watch and assess its condition before the lender finalizes the collateral value. Authentication can involve examining identifying details, movement, components, and consistency with the claimed reference and provenance. The specialist may also look for replaced or modified parts, damage, prior repairs, or signs that the watch needs service.
Authentication does not guarantee a particular valuation, and it does not eliminate every risk. Ask who performs the examination, whether the specialist works independently or for the lender, what the inspection covers, and whether the lender will provide written findings. Also clarify who pays for inspection, transport, insurance, and storage, and whether any of those costs are refundable if the loan does not proceed.
APR on a Collateral Loan: Look Beyond the Stated Rate
The stated interest rate tells you one part of the borrowing cost. The APR on a collateral loan is intended to express the annualized cost of credit, but the exact calculation and required disclosures depend on the loan and applicable law. Fees can change the effective cost substantially, especially on a short-term loan.
Ask the lender to list every charge, including any origination or arrangement fee, appraisal or authentication fee, storage and insurance charge, wire fee, renewal fee, late fee, and extension charge. Confirm which costs the lender includes in its APR figure and which costs it treats separately. A low-looking rate does not necessarily mean a low-cost loan if substantial fees apply.
Loan detail What to confirm Why it affects cost Interest rate and calculation Annual rate, daily or monthly method, and day-count convention These determine how interest accrues and how the lender calculates each charge. Fees Amount, timing, refundability, and inclusion in APR Fees add to the cash cost even if they do not reduce the principal balance. Term and payoff Due date, renewal options, payoff quote, and early repayment rules A short term may require repayment before business cash flow recovers. Collateral and default Storage, insurance, sale process, notice, and any remaining debt The contract controls what happens to the watch if you miss repayment.Speed Versus Cost for a Small Business
A watch-secured loan may move on a different timetable from an SBA loan or bank line of credit because the lender focuses heavily on the collateral. That does not make every watch loan fast. The timeline depends on scheduling an inspection, authenticating the watch, agreeing on value and terms, completing documentation, and releasing funds. Ask the lender for the expected time for each step and what could delay it.
Compare that timeline and total cost with other realistic options. A bank line may take longer to arrange but may suit recurring working-capital needs. A watch-secured loan may fit a short, specific gap if the borrower has a credible repayment source and understands the collateral risk. It can be a poor fit if the business needs ongoing cash or has no clear plan to repay principal at maturity.
Build a cash-flow schedule before signing. Include the expected date customer payments arrive, payroll dates, supplier obligations, loan interest, fees, and the principal payoff date. If repayment depends on a customer paying on time, consider what happens if that payment is delayed.
What it means for payroll
Borrow only when the business can identify a realistic source and date for repayment, so today’s payroll bridge rolex authentication process does not become next month’s payroll shortfall.
Collateral Risk and Personal Guarantees
Read the default and remedies sections carefully. If you fail to pay, the lender may have the right to take possession of and sell the watch, subject to the agreement and applicable law. Ask how the lender gives notice, how it determines the sale method and price, and whether sale proceeds first cover interest, fees, and principal.
Do not assume that pledging a watch limits your liability to the watch alone. The agreement may allow the lender to pursue a deficiency if the sale proceeds do not cover the debt, or it may include other recourse. It may also ask for a personal guarantee. A personal guarantee can make an individual responsible for business debt beyond the pledged collateral; the exact effect depends on the document and law. Ask plainly: Is this loan recourse, is there a personal guarantee, and can the lender seek more than the watch? Have a qualified adviser review unclear terms before you sign.
A Practical Checklist Before You Borrow
- Get the interest rate, calculation method, day-count basis, and sample monthly interest charges in writing.
- Request the complete fee schedule and an APR calculation that explains what it includes.
- Ask how the lender values the watch and how it uses publicly tracked secondary-market pricing data.
- Confirm that a qualified specialist will authenticate the watch and assess its condition.
- Verify the loan amount, LTV, repayment dates, maturity payment, renewal terms, and early payoff rules.
- Review custody, storage, insurance, default remedies, sale procedures, recourse, and any personal guarantee.
- Compare the loan’s total cost and funding timeline with bank, SBA, and other available financing.
Interest on a watch-secured loan is usually calculated from the amount borrowed, the rate, and the time the balance remains outstanding—but the contract supplies the details that determine the real cost. A Rolex’s secondary-market liquidity may help a lender assess collateral, while public pricing data and expert authentication can inform that assessment. Neither guarantees a loan amount or a favorable rate. For a business owner, the practical test is whether the funding arrives in time, the total cost fits the cash-flow plan, and the repayment terms protect both the business and the watch.